Branch Transformation
ABOC keeps the focus on Chicago through headquarters expansion
ABOC is expanding in top commercial spaces in Chicago, but is still keeping its connection to the labor movement
November 2, 2026 by Bradley Cooper — Editor, Connect Media
 ChatGPT
 Grok
 Perplexity
 Claude
ABOC has had a long history in the Chicago community. First launched in 1922 by a workers' union, it has remained intimately tied to the organized labor movement in Chicago. In 2024, it rebranded from Amalgamated Bank of Chicago to ABOC, and has continued that fresh look through its new headquarters in the Chicago Loop.
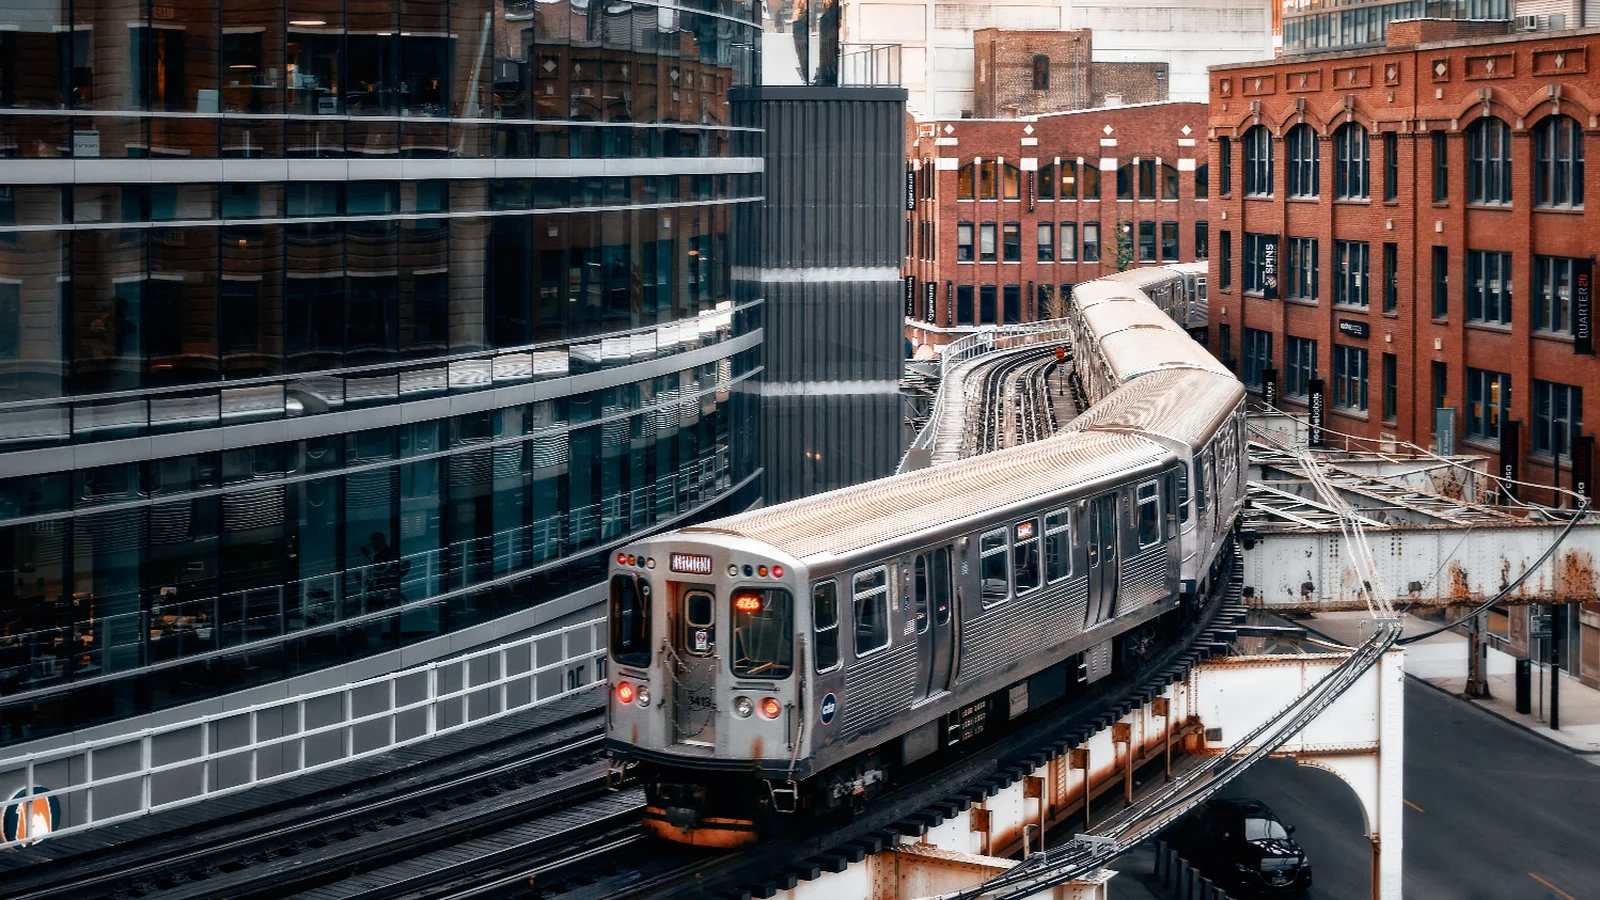
This headquarters isn't just a fresh location; it was selected due to its closer location to public transit, enabling customers to more easily access financial services. ATM Marketplace reached out to Andy DeMotte, Senior Vice President of Marketing at ABOC, to discuss how its history informs its services and approach to customer experience, ATMs and self-service banking.
Q: Can you share some background on ABOC's history?
DeMotte: Amalgamated Bank of Chicago (ABOC) was founded in 1922 by the Amalgamated Clothing Workers Union, now Workers United, to serve local businesses and working people. Organized labor remains central to the bank's identity, with continued union ownership and representation among its employees and Board of Directors. ABOC also has a long history of retail banking innovation, including offering one of Chicago's first drive-through tellers. Over the past century, the bank has evolved alongside Chicago while expanding its services to meet the needs of unions, businesses and individuals.
Q: What has ABOC's branch development looked like over time?
DeMotte:Historically, ABOC had one large branch in downtown Chicago; over time, the footprint, staff, and teller windows have decreased as more of the bank's customers moved to remote banking. In 2007, the Bank opened a second branch in Warrenville, Illinois, to service a growing union and corporate presence in the suburbs.
Q: How has ABOC's branch strategy evolved over time?
DeMotte: Many of the Bank's activities (such as Corporate Trust or Treasury Management) do not drive much, if any, walk-in traffic, so there has not been serious consideration to opening a second branch in the city. As noted above, the Bank did open a second branch in Warrenville to accommodate its growing base of customers in the Western suburbs.
Q: What drove the decision to relocate ABOC's headquarters to the Chicago Loop?
DeMotte: The bank has had a presence in the Loop since its founding in 1922 – the most recent location at 30 N. LaSalle is about a quarter-mile east of ABOC's new location. However, the branch offers improved accessibility and convenience, and dedicated banker offices, teller, and customer service areas – all intended to provide better service and a better customer experience. Lastly, the new location is more easily accessible via public transportation and expressway.
Q: What is ABOC's current ATM strategy? Does the bank currently use, or have plans to use, Interactive Teller Machines (ITMs)?
DeMotte:The bank is unlikely to increase the number of ATMs in its branches – currently, there are machines inside both of ABOC's branches as well as a drive-through in its suburban location. There has been preliminary discussion of implementing ITMs with key clients – for example, implementing an ITM in the lobby of a major labor union where we bank a significant number of their members. There is no concrete timeline for implementing this technology at the moment, however.
Q: How does ABOC approach self-service banking overall?
DeMotte:Both consumer and commercial customers have access to the basics of self-service banking – there is an app available which they can use for account hygiene, checking their balance, etc.; the company website has a robust online banking platform where customers can perform maintenance functions, schedule payments, etc., and Zelle is available for consumer customers to transfer funds quickly. However, ABOC's key point of differentiation is that the Bank provides individualized, tailored "white glove" service to its valued clients – so although customers are welcome to take advantage of self-service functions for the sake of convenience, customers are encouraged to work directly with their ABOC Account Officer to manage complex transactions and streamline their workflow.
Q: How is ABOC currently using AI, or exploring opportunities to incorporate AI into its operations and customer experience?
DeMotte: ABOC is not currently using AI.
Q: Is there anything else you'd like to highlight about ABOC's growth, technology strategy or future plans?
DeMotte: ABOC is focused on building on its more than 100-year history while positioning the bank for its next phase of growth. As part of that evolution, ABOC's recent rebranding better reflects the forward-looking, digital-first and growth-oriented institution it has become, with deep expertise in union banking, commercial real estate lending and municipal, commercial and corporate trust services. The new brand is designed to showcase what has long differentiated ABOC behind the scenes: extraordinary expertise, highly personalized service and a commitment to standing side by side with clients as they navigate complex, high-stakes financial decisions. Looking ahead, ABOC will continue investing in technology and expanding access to its expertise while maintaining the relationship-driven approach that has defined the bank for more than a century.
About Bradley Cooper
Bradley Cooper is an experienced editor for Connect Media. He has written across a wide range of beats, ranging from food to digital signage to banking, and is the current editor of ATM Marketplace and Food Truck Operator. His background is in information technology, advertising, and writing. When he’s not crafting a story, you can find him going for a run or spending time with his wife and three sons.
Related Media
Featured Vendor
Grow faster using DPL’s AI Powered Hercules Platform featuring built-in RMS. Level the playing field with unparalleled remote management capability. Spend less time putting out fires and more time landing locations with DPL’s managed wireless service, referred to as the “gold standard” amongst operators.
Subscribe
Get the latest news and resources from ATM Marketplace.